Introduction
Sending or receiving money internationally, you've likely come across terms like SWIFT, BIC, intermediary bank, and wire transfer. What's usually less clear is what actually happens after you hit send. This guide breaks down how a cross border wire transfer really works, what it costs, how long it typically takes, and what Indian businesses specifically need to keep in mind.
What Is a Cross Border Wire Transfer
A cross border wire transfer is an electronic bank transfer used to send or receive funds between parties in different countries. The RBI describes it the same way, as a wire transfer where the originator and beneficiary banks sit in different countries.
No physical currency actually travels anywhere. Banks use electronic instructions and their account relationships with each other to make the funds available at the other end. An Indian SaaS company receiving USD 10,000 from a US customer, for instance, sees that money land in its Indian bank account only after it has passed through the relevant banking and settlement chain.
Why Wire Transfers Matter
Wire transfers give businesses and individuals a reliable, bank backed way to make legitimate international payments. They show up constantly in international invoices, supplier payments, export proceeds, imports, investments, and education payments. An Indian exporter gets paid this way by an overseas buyer, and an Indian business pays a foreign software vendor the same way.
Speed and tracking matter more than ever here. Swift reported in 2026 that 75 percent of payments sent over its network reach the destination bank within 10 minutes or less, though delays can still crop up before the money actually reaches the beneficiary.
How Does a Cross Border Wire Transfer Actually Work
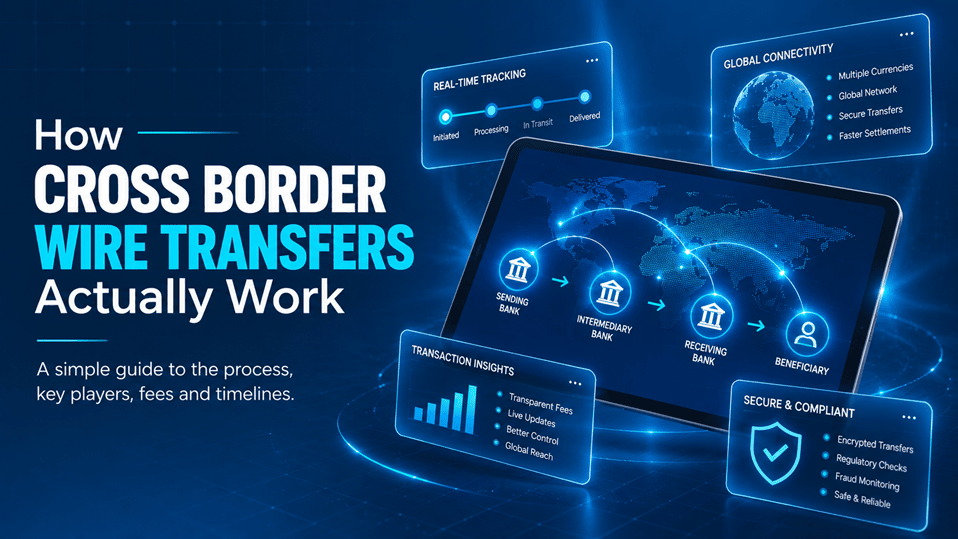
A wire transfer moves through a chain of instructions and banking relationships before it reaches the beneficiary. The exact route depends on the countries, currencies, and banks involved.
Step One: The Sender Gives Payment Instructions
The sender tells their bank how much to send and to whom, including the beneficiary's name, account details, bank information, currency, amount, and often the reason for the payment. Indian company paying a US supplier would hand over the supplier's account number, routing details, SWIFT or BIC code, and the USD amount involved.
Step Two: The Sending Bank Processes It
The bank checks the payment and runs its compliance checks before doing anything else, reviewing customer information, the purpose of the transaction, and any sanctions related checks that apply.
Step Three: The Instructions Travel Through the Network
The bank then sends the payment instructions through the relevant messaging infrastructure. It is worth being clear here: SWIFT is a messaging network. It does not hold customer funds and it is not the bank actually settling the payment.
Step Four: Correspondent Banks May Step In
If the sending and receiving banks do not have a direct relationship for that currency or corridor, one or more correspondent banks step in to bridge the gap.
Step Five: The Beneficiary Bank Credits the Account
Finally, the beneficiary bank receives the payment, runs its own checks, and credits the recipient's account.
Wire Transfer vs SWIFT Transfer: What Is Actually the Difference
A wire transfer describes the electronic movement of funds. SWIFT refers to the messaging infrastructure banks use to exchange payment instructions. People use these terms interchangeably in everyday conversation, but they describe two different parts of the same payment.
A bank might send its instructions through SWIFT while the actual funds settle through correspondent accounts and other banking arrangements entirely. This distinction matters a lot when you are trying to figure out where a delayed payment actually is, because the message can move fine while the money is still waiting somewhere else in the chain.
Is SWIFT Responsible for Moving the Money
No. SWIFT connects more than 11,500 financial institutions across over 200 countries and territories, but it only carries the messaging, not the money itself. A SWIFT message reaching the beneficiary bank quickly does not automatically mean the beneficiary has the funds yet, since domestic processing and account crediting can still take additional time.
What Information Do You Actually Need for an International Wire Transfer
You will generally need the beneficiary's name, their account number or IBAN where applicable, the beneficiary bank's name, the SWIFT or BIC code, the bank's address where required, the currency and amount, the purpose of the payment, your own sender details, and any supporting documents your bank asks for. An exporter receiving USD, for example, may need to submit invoice details alongside the transfer depending on the nature of the export.
What Is a SWIFT or BIC Code
It is simply an identifier that tells the payment system which financial institution to route the money to. Your bank will usually ask for the beneficiary bank's SWIFT or BIC code alongside their account number. Requirements do vary by country though, some rely on IBANs instead, others use different routing identifiers entirely.
What Is a Correspondent Bank
A correspondent bank is simply a bank that provides banking services to another bank it does not have a direct relationship with. If Bank A in India needs to send USD but has no direct tie to the beneficiary's bank in the US, it might route the payment through Bank B in the US as a correspondent. This extra hop can affect both cost and how long the transfer takes.
How Much Does a Cross Border Wire Transfer Actually Cost
The total cost usually stacks up from several pieces rather than one single fee. Here is what to actually look at.
| Cost component | What it actually means |
|---|---|
| Sending bank fee | Fee charged by the bank that originates the transfer |
| Correspondent fee | Charge applied by an intermediary bank, where one is involved |
| Receiving bank fee | Fee the beneficiary bank may charge before crediting the account |
| FX spread | Gap between the reference exchange rate and the rate you are actually given |
| Taxes or statutory charges | Any charges that apply to the transaction or the customer |
The amount that lands in the beneficiary's account can end up lower than what was sent once intermediary deductions and FX conversion are factored in. A business sending USD 10,000 should not judge the transaction by the advertised transfer fee alone. Swift itself notes that its newer cross border payments framework is built specifically to improve cost transparency and full value delivery.
How Long Does an International Wire Transfer Take
Timing depends on the payment route, the currencies involved, the banks in the chain, cut off times, holidays, and compliance checks. A payment submitted before your bank's cut off time follows a different processing schedule than one submitted right after it, or during a local holiday.
Swift reported that 80 percent of the average cross border payment journey can happen in the last mile, after the payment has already reached the beneficiary's bank, which explains why fast network transmission does not always mean a fast final credit. Separately, nearly 60 percent of Swift GPI payments get credited to end beneficiaries within 30 minutes, and almost all of them within 24 hours, though these figures apply specifically to GPI payments rather than every transfer.
Why Do Cross Border Wire Transfers Get Delayed
Delays usually trace back to a handful of common causes: incorrect account numbers or beneficiary details, missing or wrong SWIFT or BIC information, compliance or sanctions screening, missing purpose codes, extra documentation requests, intermediary bank processing, weekends and public holidays, currency or country specific restrictions, or simple processing delays at the beneficiary bank. A payment can technically reach the destination bank and still sit pending while the bank works through its own checks.
Can an International Wire Transfer Be Rejected or Returned
Yes. This tends to happen when required information is incorrect, compliance requirements are not met, or the receiving institution simply cannot process the payment as submitted. An incorrect beneficiary account number, for instance, can get a payment rejected or bounced back after it has already been processed. Double checking beneficiary details before submitting saves everyone the trouble.
How Do Cross Border Wire Transfers Work in India
Transfers involving India follow applicable banking, foreign exchange, and regulatory requirements, and the exact rules depend on whether the payment is inward or outward and what it is for. For inward payments, authorised dealer banks in India process foreign remittances coming through banking channels. An Indian software exporter receiving payment from an overseas customer, for example, may need specific transaction and export documentation depending on the nature of the service.
What RBI and FEMA Requirements Actually Apply
These depend on the nature and purpose of the transaction, which is exactly why it is worth confirming the specifics with your authorised dealer bank rather than assuming one rule covers everything. RBI's wire transfer requirements call for accurate originator and beneficiary information on every cross border transfer. Exporters should also know that documentation can vary by export type, with specific provisions covering things like software export realisations and foreign currency inward remittances.
Wire Transfer vs Cross Border Payment Platform
A traditional wire transfer runs mainly on bank to bank infrastructure. A digital cross border payment platform adds a technology layer on top for collecting, converting, routing, tracking, and reconciling international payments. Here is how they stack up against each other.
| Factor | Bank wire transfer | Digital payment platform |
|---|---|---|
| Payment infrastructure | Banking network | Platform plus regulated payment partners |
| User experience | Usually bank led | Often digitally managed |
| FX visibility | Depends on your bank | Depends on the provider |
| Tracking | Depends on the bank or service used | Often comes with dashboard tracking |
| Best suited to | Broad, general international payments | Specific, recurring business payment workflows |
An Indian SaaS company might receive customer payments either through a straightforward bank wire or through a platform offering virtual accounts and digital reconciliation, depending on what suits its volume and workflow better.
How Can Businesses Actually Reduce Wire Transfer Costs
Start by comparing the effective FX rate rather than the advertised transfer fee, since a low fee can easily be offset by a wide FX spread. Then check whether intermediary charges get deducted along the way, and confirm whether the receiving bank charges anything on its end. A business receiving USD 20,000 should compare the actual INR amount it expects after conversion and all applicable charges, rather than comparing two headline fees side by side.
Where Wire Transfers Show Up in Practice
An Indian SaaS company receives USD 15,000 from a US customer against an invoice. An Indian exporter gets paid by an overseas buyer for shipped goods. An Indian importer pays a supplier abroad in USD or another agreed currency. A professional services firm collects international fees for consulting, design, or software work. Different businesses, same underlying mechanism.
How Should You Prepare Before Sending a Wire Transfer
Getting the beneficiary information, payment purpose, currency, fees, FX rate, and documentation sorted out ahead of time avoids a lot of avoidable delays. Run through this before you send anything.
- Verify the beneficiary name and account details
- Confirm the SWIFT or BIC code, or whatever identifier is required
- Check the currency and the exact amount
- Ask about sending, intermediary, and receiving charges
- Compare the actual FX rate and markup being applied
- Confirm the transaction purpose and any required documentation
- Check the bank's cut off time and expected processing window
- Keep the payment reference and transaction confirmation
- Track the payment wherever tracking is available
- Retain the relevant invoices and regulatory documentation
Indian businesses should loop in their authorised dealer bank whenever a transaction touches specific RBI, FEMA, tax, export, or foreign exchange requirements.
Conclusion
A cross border wire transfer is a lot more than typing in an account number and hitting send. It involves payment instructions, banking relationships, FX conversion, compliance checks, and settlement, all happening one after another.
Understanding how SWIFT, BIC codes, correspondent banks, fees, processing times, and regulatory requirements fit together helps businesses plan international payments with fewer surprises. For Indian businesses specifically, checking the transaction purpose and the applicable RBI and FEMA documentation upfront makes the whole process considerably smoother. Accurate beneficiary information, transparent pricing, and real visibility into the payment route are what actually make international payments easier to manage.